MANILA, Philippines – The Marcos estate tax controversy has returned to the spotlight as the Bureau of Internal Revenue (BIR) faces renewed pressure to collect the family’s reported ₱203.8-billion tax liability. Civil society coalition 1Sambayan is urging the government to take appropriate legal action before December 2, 2026, warning that delays could affect the state’s ability to pursue the decades-old tax obligation.
The coalition 1Sambayan has urged newly appointed BIR Commissioner Rolando Ligon Jr. to take immediate steps to protect the government’s collection rights, raising concerns over the approaching deadline and the possibility that the long-standing tax liability could become more difficult to collect.
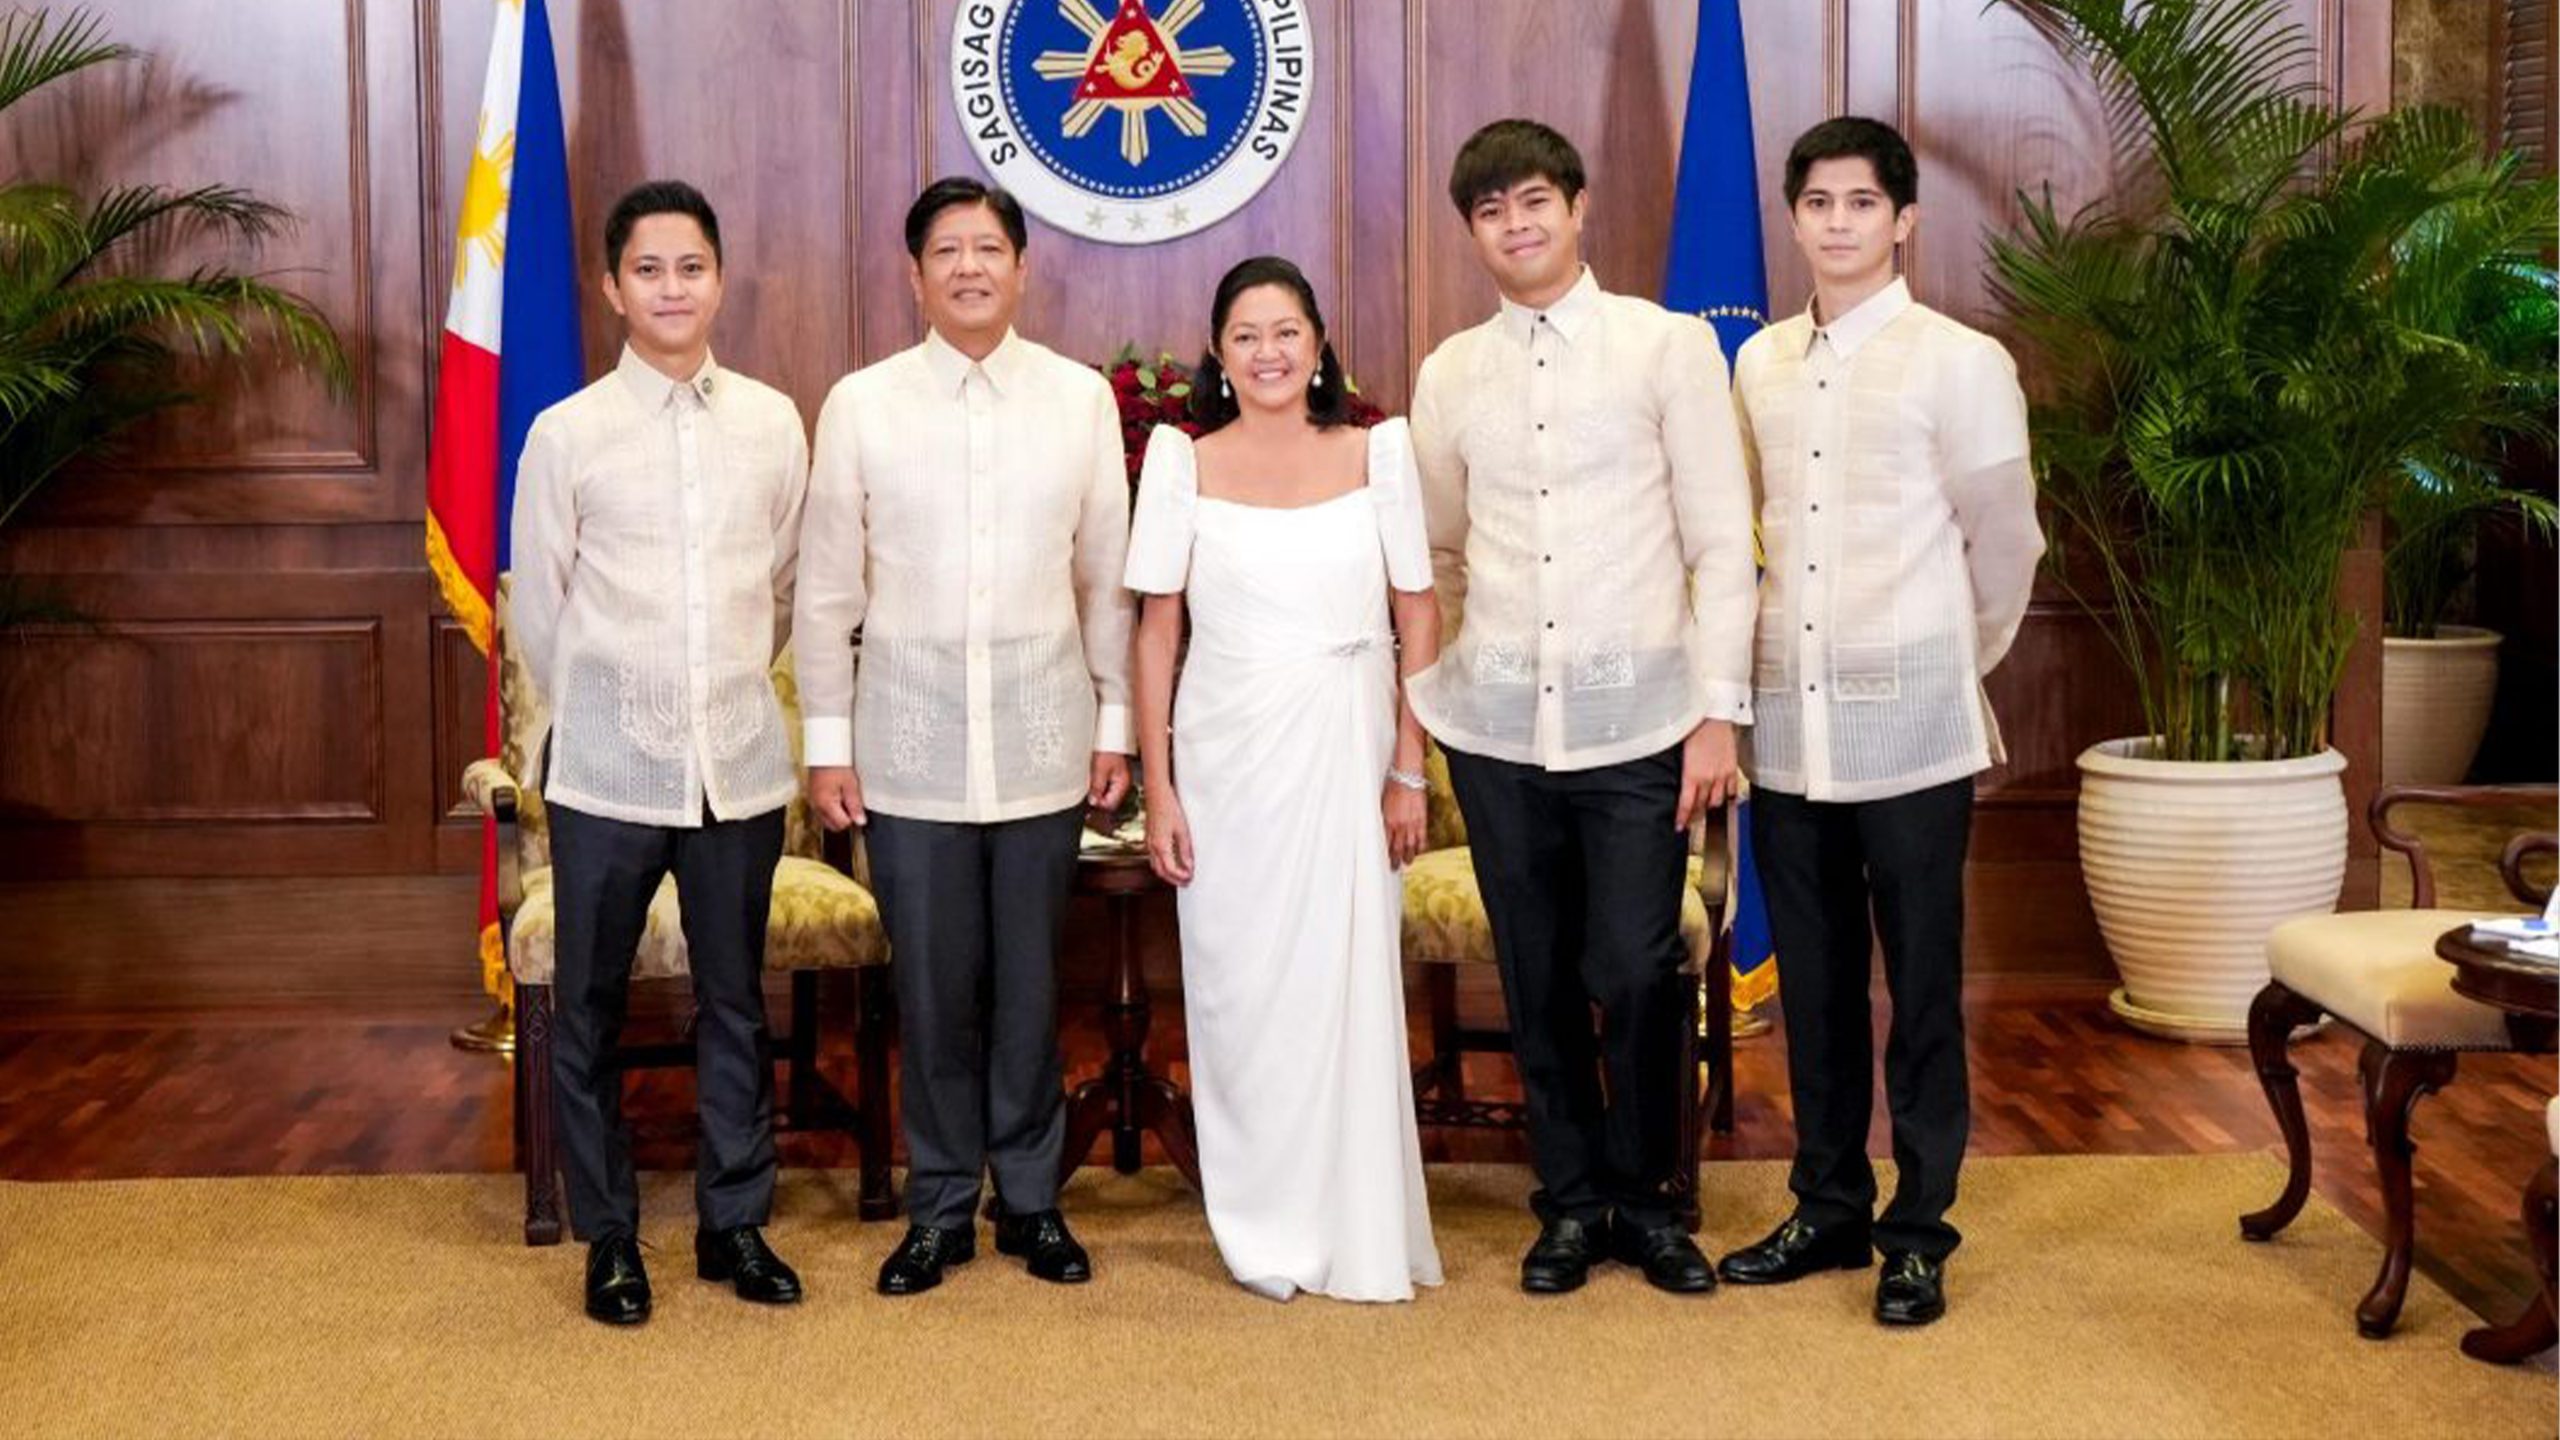
The controversy involves the estate of former President Ferdinand Marcos Sr., whose estate was assessed billions of pesos in unpaid taxes following his death in 1989.
Estate tax liability dates back to 1991
The dispute began when the BIR issued a deficiency estate tax assessment on July 26, 1991, amounting to approximately ₱23.29 billion.
The assessment covered estate taxes arising from the properties and assets left by the former president.
The Marcos heirs challenged the government’s assessment, but the case eventually reached the Supreme Court.
In its June 5, 1997 decision in Marcos II v. Court of Appeals (G.R. No. 120880), the Supreme Court upheld the government’s position and recognized the validity of the BIR’s collection measures.
The ruling became final and executory in 1999, according to subsequent accounts of the case.
The original assessment reportedly grew to approximately ₱203.8 billion due to accumulated interest, penalties and surcharges.
BIR sent a written demand in December 2021
The BIR confirmed in March 2022 that it had sent a written demand to the Marcos heirs on December 2, 2021, seeking payment of the outstanding estate tax liability.
The confirmation renewed public attention to the decades-old tax controversy and the government’s efforts to collect the amount.
However, the approaching December 2, 2026 date has raised a new legal question concerning the applicable prescription period for collecting assessed taxes.
Under the National Internal Revenue Code, the government is generally subject to statutory periods for collecting tax assessments, although certain circumstances and enforcement proceedings can affect how those periods are computed.
1Sambayan has warned that the government must take the necessary legal steps to preserve its collection rights before the period it considers critical expires.
The coalition’s position has placed renewed attention on whether the BIR needs to issue and properly serve another written demand or undertake other enforcement measures.
Legal questions remain over the collection period
The approaching deadline does not necessarily mean that the government will automatically lose its right to collect the entire amount if no new demand letter is issued.
The legal status of earlier enforcement actions is an important consideration.
Records of the Supreme Court case show that the BIR had already undertaken collection measures, including notices of levy on real properties in 1993.
Legal provisions also recognize circumstances in which the period for collecting taxes may be suspended.
Consequently, determining whether the government’s collection rights are approaching prescription requires examining the original assessment, previous enforcement proceedings and subsequent legal actions.
A demand letter alone does not automatically restart the statutory collection period.
The BIR’s official position on the precise legal effect of the December 2021 demand and the approaching December 2026 date remains important in resolving the issue.
Public accountability and billions in potential government revenue
The reported ₱203.8-billion liability has also become an issue of public accountability, given the amount of revenue potentially involved.
The amount represents substantial resources that, if successfully collected, could contribute to government programs and public services.
These include education, healthcare, infrastructure, agricultural assistance and social welfare initiatives.
However, the government must first establish and enforce its legal right to collect the outstanding liability before any such revenue can be realized.
The controversy also raises questions about the consistency of tax enforcement, particularly when the government pursues ordinary taxpayers over unpaid obligations while a major estate tax liability remains unresolved decades after its original assessment.
BIR response and Marcos family’s position remain important
With December 2 approaching, attention is now focused on whether the BIR will publicly clarify the status of its collection proceedings and explain what additional measures, if any, are necessary.
An updated official computation of the estate’s outstanding liability would also help establish whether the reported ₱203.8-billion figure remains accurate.
The position of the Marcos heirs and their legal representatives is likewise relevant to providing a complete account of the dispute.
For now, the issue goes beyond the amount of unpaid taxes. It concerns the government’s ability to enforce a final court ruling, protect public revenue and demonstrate that tax obligations are pursued consistently regardless of the individuals or families involved.
As the deadline identified by 1Sambayan draws closer, the BIR’s next actions could become a significant test of the government’s commitment to collecting one of the country’s most prominent outstanding tax liabilities.
Sources: Supreme Court of the Philippines, Marcos II v. Court of Appeals (G.R. No. 120880, June 5, 1997); Bureau of Internal Revenue confirmation reported in March 2022; The Philippine Star reporting on 1Sambayan’s November 2026 appeal; National Internal Revenue Code of the Philippines.
 Facebook
 Twitter